The value of a well lies not in how much water is drawn at one time, but in whether the water level returns on its own. This third-quarter report from Gujing Gongjiu is about reading the water level of that well.
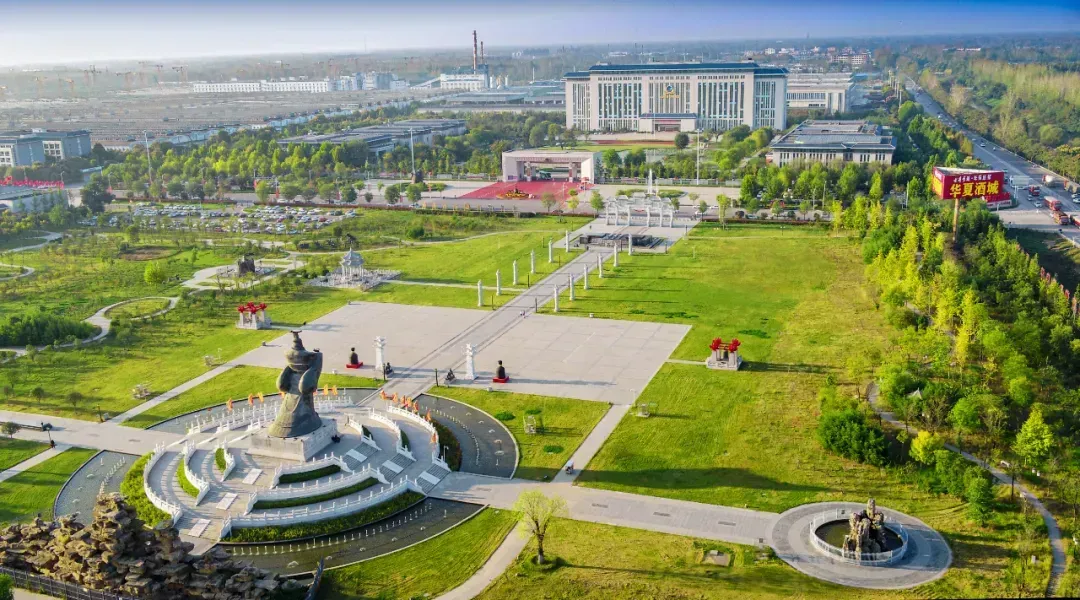
In Gujing Town, Bozhou, there is an ancient well dating back to the Northern Wei Dynasty. Its water has never dried up over a thousand years, and the words “Gujing” in Gujing Gongjiu come from this well.
Borrowing this image to read the third-quarter report released on October 29, many figures suddenly take on a different meaning. In the first three quarters, revenue reached RMB 12.770 billion and net profit attributable to shareholders reached RMB 2.260 billion. Based on data from listed baijiu companies that have disclosed their 2026 third-quarter reports, Gujing Gongjiu ranks among the top five in the industry by revenue, with its position moving further forward. Third-quarter revenue was RMB 2.639 billion, up 3.69% year-on-year, making it one of the few liquor companies among those that have disclosed third-quarter reports to achieve positive single-quarter revenue growth.
Whether a well is good does not depend on how urgently a single ladle of water is scooped, but on whether the well wall is solid, whether the water level is stable, and whether the water source has been cut off. In the view of JiuYe Times, the value of Gujing’s third-quarter report lies not in the level of the single-quarter profit line, but in the fact that the three water levels of this well — the well wall of quality, the water level of channels, and the spring of the brand — are all moving in a healthy direction.
PART 01
The Well Wall: Quality Upgrading Is the Brick That Keeps the Well from Collapsing
A well must first have walls before it can hold water.
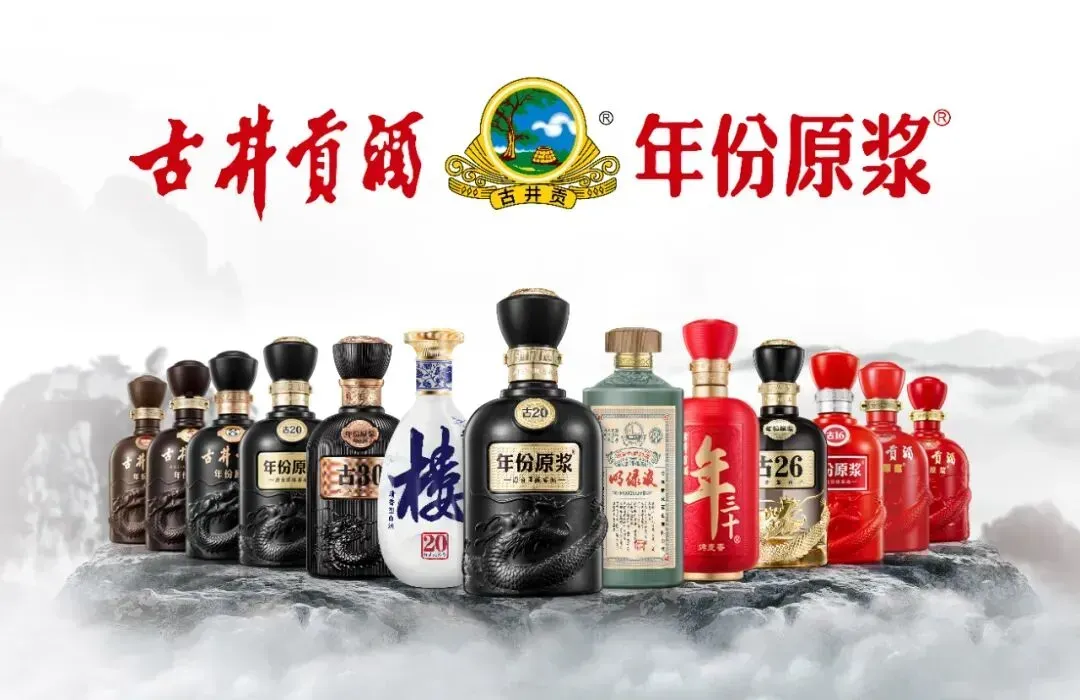
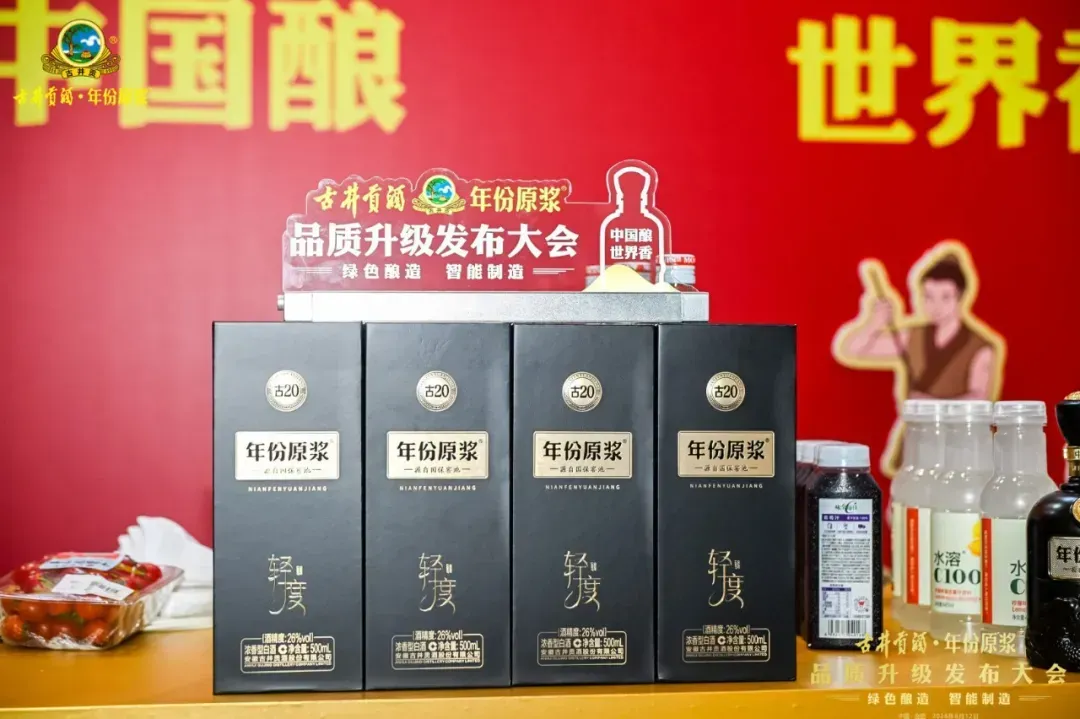
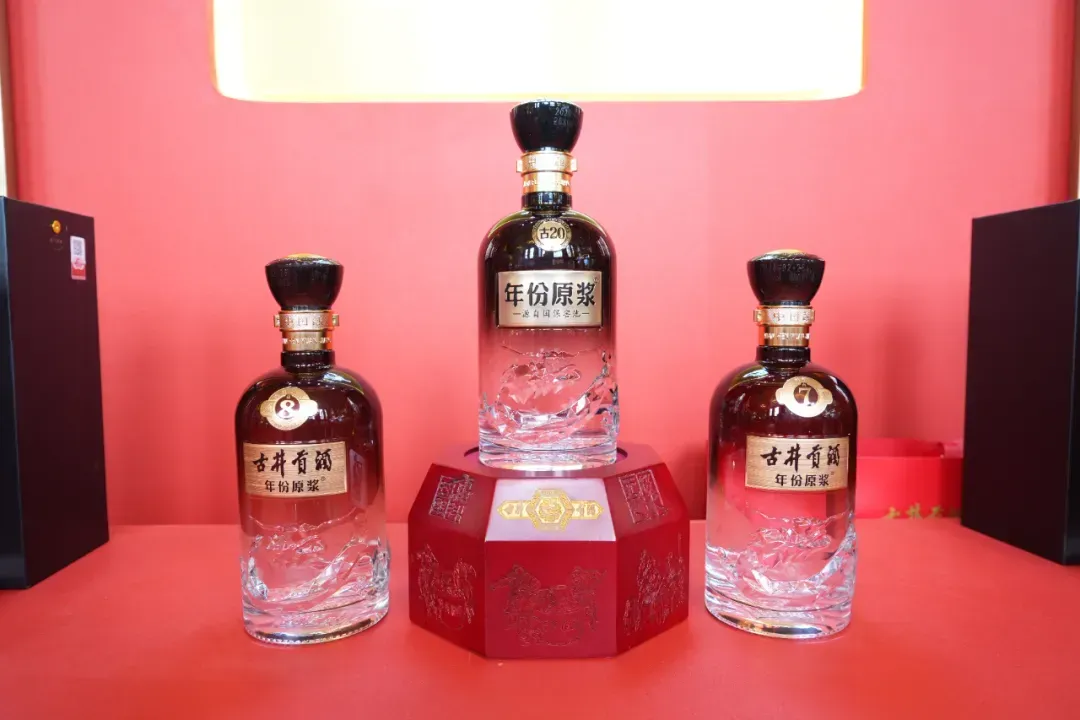
In August this year, the entire Vintage Pulp series — from the Gift Edition, Gu 5, Gu 7, Gu 8 to Gu 16 and Gu 20 — completed a systematic quality upgrade, explicitly proposing “quality improved, price unchanged.” The basis for the upgrade was not a craft narrative produced behind closed doors, but the results of market taste feedback, terminal suggestions, and visits to more than 100 terminals over the past two years, involving multi-dimensional iteration from process details and liquor-body flavour to sensory experience. Gu 16 also increased the proportion of aged liquor from Ming and Qing dynasty nationally protected fermentation pits, directly raising the body thickness of the core product.
Whether this “well wall” is laid solidly determines whether all subsequent channel actions have a place to land.
In a cycle where consumers are becoming more rational, leaving the dividend of quality upgrading to terminals rather than converting it into price increases is equivalent to thickening the well wall without charging more for drawing water. The waist matrix formed by Gu 8, Gu 7, and Gu 5 stabilises the mass-consumption base, with mass-price products contributing about 70% of revenue — the most solid ballast at the bottom of the cycle.
The Q3 gross margin was 77.8%, down slightly by 2 percentage points year-on-year, still at a high level in the baijiu industry. The small fluctuation in gross margin does not mean the well wall has loosened; rather, the cost of laying the wall has been proactively front-loaded.
PART 02
The Water Level: Contract Liabilities and Cash Collection Are Signals That the Well Water Is Returning on Its Own
Once the well wall is built, what truly needs to be observed is the water level.
At the end of Q3, Gujing’s contract liabilities balance was RMB 958 million, up 15.42% quarter-on-quarter (though still somewhat lower than at the beginning of the year); cash received from sales in the quarter was RMB 3.28 billion, up 41.4% year-on-year, with cash collection growth significantly outpacing revenue. Channel research shows that Gujing’s terminal inventory has fallen to one-half to one-third of the level in the same period last year, with ordinary stores holding less than one month of inventory — a fairly healthy level within the baijiu industry.
In the financial reporting system, contract liabilities are often broadly called a “reservoir.”
But within the framework of the “well,” it is more like a water-level gauge.
Information asymmetry theory shows that market participants hold differing information, and those with more frontline information will use actionable behaviour to convey their expectations. Distributors perceive terminal sell-through earlier than financial statements. When channels still have inventory on hand but are still willing to pay real money to the distillery in advance, this action itself is a vote on their willingness to cooperate in subsequent operations.
In the view of JiuYe Times, what truly needs to be repaired during the baijiu adjustment period is not revenue growth, but the channel balance sheet. The water level rising and cash collection running ahead of revenue indicate that this balance sheet is moving in a healthy direction. The well water is not being pumped up — it is returning on its own. This distinction carries more information than a single quarter’s profit figure.
PART 03
The Spring: Banquet Scenarios and the Autumn Brewing Expo Are Two Different Water Sources
For a well not to dry up over the long term, it cannot rely on only one spring.
The first spring is on the banquet table.
Gu 16 is positioned in the RMB 300–400 price band, focusing on high-end urban banquets, precisely hitting the pressure point of this round of consumption migration: the downgrading of business consumption and the rationalisation of banquet liquor have pushed some demand that originally belonged to higher price bands into this range.
During the Mid-Autumn and National Day double festivals, Gu 16 achieved sell-through growth of more than 10% in banquet scenarios. This is the most direct source of sell-through in the current period, and also the product-side explanation for the quarter-on-quarter rebound in contract liabilities.
The second spring is farther away.
On September 19, the 13th Gujing Gongjiu · Vintage Pulp Autumn Brewing Ceremony was held in Bozhou. This brand IP, now in its thirteenth year, has already moved beyond a single ceremony: Gujing Gongjiu, Huanghelou Liquor, Mingguang Liquor, and Jiuyun Liquor brewed simultaneously across four locations, with eight major production bases starting brewing in sync; the first autumn-brewed liquor was jointly auctioned online with JD.com for the first time; brand ambassador Louis Koo attended; and Guqi Herbal Whisky and Gu 20 Year of the Sheep zodiac commemorative liquor were released simultaneously.
Gujing Gongjiu has thus become the only domestic baijiu brand to have appeared on the World Expo stage for six consecutive editions and to have become an official partner of the China Pavilion at five editions. It has also launched strategic cooperation for the China Pavilion at Expo 2027 Belgrade, with overseas business covering more than 30 countries and regions.
In the view of JiuYe Times, banquets are the water that quenches thirst in the current period, while autumn brewing and the World Expo are water seeping underground. The former determines whether this quarter’s financial statements look good; the latter determines whether this well will still exist five years from now. The scarcest resource during an adjustment period is not expenses, but whether an enterprise is still willing to pay for “capabilities that cannot be used for the time being.”
PART 04
The Well’s Compound Interest: Intertemporal Allocation and the Inventory Cycle
Raising the perspective one level, Gujing’s choices this year can be read through a simple economic concept: intertemporal allocation. Given a fixed total amount of resources, an enterprise can choose to leave value in current profit or allocate it to capabilities at some future point.
Gujing has allocated part of its current expenses — through terminal cultivation, quality upgrading, and channel relief — into healthier inventory levels, more solid banquet-scenario share, and greater channel willingness to cooperate. These assets are not on the income statement, but they form the base inventory the enterprise can draw on when the next round of demand recovery arrives.
A companion concept is the inventory investment cycle.
Baijiu channel inventory is essentially an investment behaviour within the industrial chain: distributors accumulate inventory when expectations improve and cut inventory when expectations weaken. Gujing’s terminal inventory having fallen to a small fraction of last year’s level means that “de-investment” at the channel level has already gone deep, and the room for further decline is narrowing. When inventory no longer acts as a drag, marginal improvements in revenue are more easily amplified by channel behaviour.
The interim dividend plan, within this framework, is not merely a shareholder return arrangement. It simultaneously conveys a judgement to channels and investors: this well has a certain capacity to produce water, and a certain rhythm of repair. In a cycle of weak expectations, certainty itself has option value.
The wisdom of a well lies in the fact that it never seeks to be filled to the brim in one go. When the water level is low, it stores; when the well wall loosens, it builds; when springs are few, it finds new ones.
In Gujing Gongjiu’s third-quarter report, positive revenue growth and a forward move in ranking are ripples on the surface; quality upgrading, channel cash collection, and autumn brewing and the World Expo are the well wall, water level, and spring beneath the surface. Trading short-term profit elasticity for these invisible things will not immediately stand out in financial statements, but it ensures that when the next cycle begins, the water source is still there and the well wall is still solid.
(This article is compiled from publicly available industry information. Sources/Data: Gujing Gongjiu 2026 Third-Quarter Report and Interim Profit Distribution Plan, Jianiang.com, China Fortune Network, Soochow Securities research reports, Tonghuashun industry information, etc.)