当行业大盘原地踏步、对手利润两位数增长,青岛啤酒用一份不错的中报,划出了一条属于自己的增长曲线。
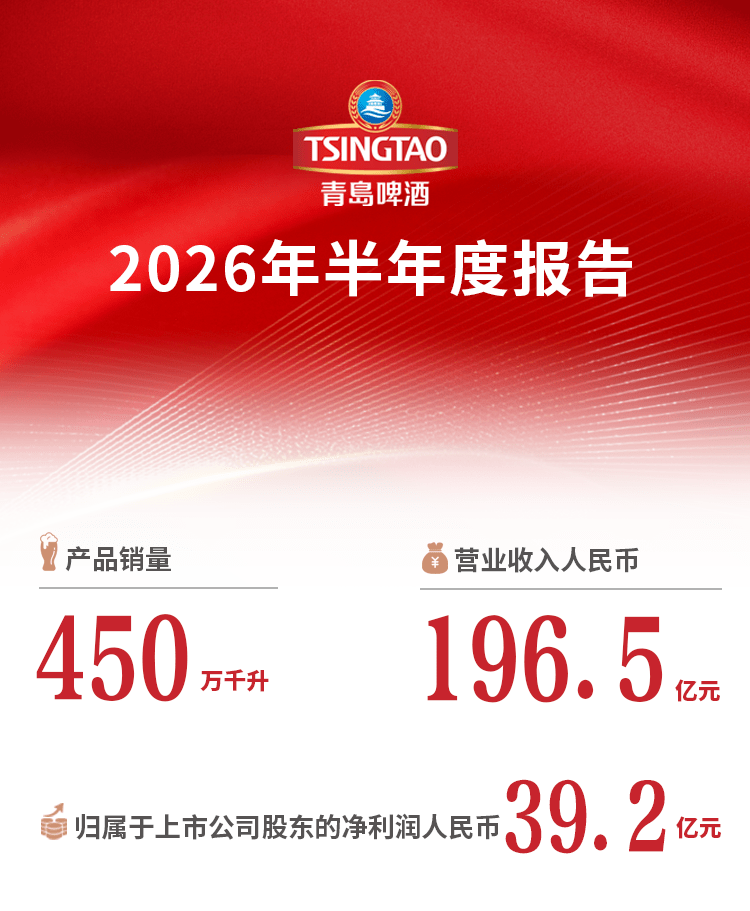
8月26日,青岛啤酒交出了2026年上半年的成绩单。
产品销量450万千升,营业收入196.5亿元,归母净利润39.2亿元。三个核心数字背后,是这家百年酒企在行业存量博弈时代交出的一份稳中求进的答卷。
但在酒业时报看来,这份财报真正的看点,不在于39.2亿这个数字本身,而在于它揭示的啤酒行业竞争逻辑的根本性转变——当总量天花板触手可及,企业之间的较量已经从“谁卖得多”变成了“谁卖得对”。
利润增长背后的“含金量”之争
先看数据。上半年营收196.5亿元,同比下降4.08%;归母净利润39.2亿元,同比微增0.4%。单看二季度,营收93.7亿元,同比下降6.7%;归母净利润21.2亿元,同比下降3.4%。
营收下滑、利润微增——这是一组看似矛盾的数据。
有分析认为利润维稳主要依赖理财收益增加、营销费用压降和原材料成本下行等因素。这确实是事实。上半年公司广告宣传费同比大幅下降33%,节约成本超2亿元。
但硬币的另一面同样值得关注:经营活动产生的现金流量净额达到55.05亿元,同比增长14.69%。在营收下滑的背景下,现金流反而大增——这说明公司的回款能力、渠道管控和现金创造效率在提升。
湘财证券在2026年5月的前期研报中提出,公司正在从“成本红利驱动的利润修复”,切换到“结构升级延续+旺季量修复”的新阶段。
利润的“体面”与否,关键看是消耗未来换来的,还是为未来蓄力换来的。从55亿的经营现金流来看,青啤属于后者。
高端化的逆势突围
在总量萎缩的背景下,青岛啤酒的高端化战略正在兑现。
上半年,主品牌青岛啤酒实现销量270.8万千升,其中中高端以上产品销量204.4万千升,同比增长2.6%。这意味着中高端产品在主品牌中的占比已超过75%。
横向对比更能说明问题。2026年上半年全国啤酒产量同比仅微增0.2%,行业大盘基本持平。华润啤酒啤酒业务营收236.7亿元、同比增长2.2%,次高及以上销量增幅超10%;燕京啤酒营收90.31亿元、同比增长5.53%,归母净利润13.99亿元、同比大增26.86%;而重庆啤酒营收85.76亿元、同比下降2.98%,归母净利润7.96亿元、同比下降7.98%。
头部企业出现了明显的分化——高端化推进得越深,抗周期能力越强。
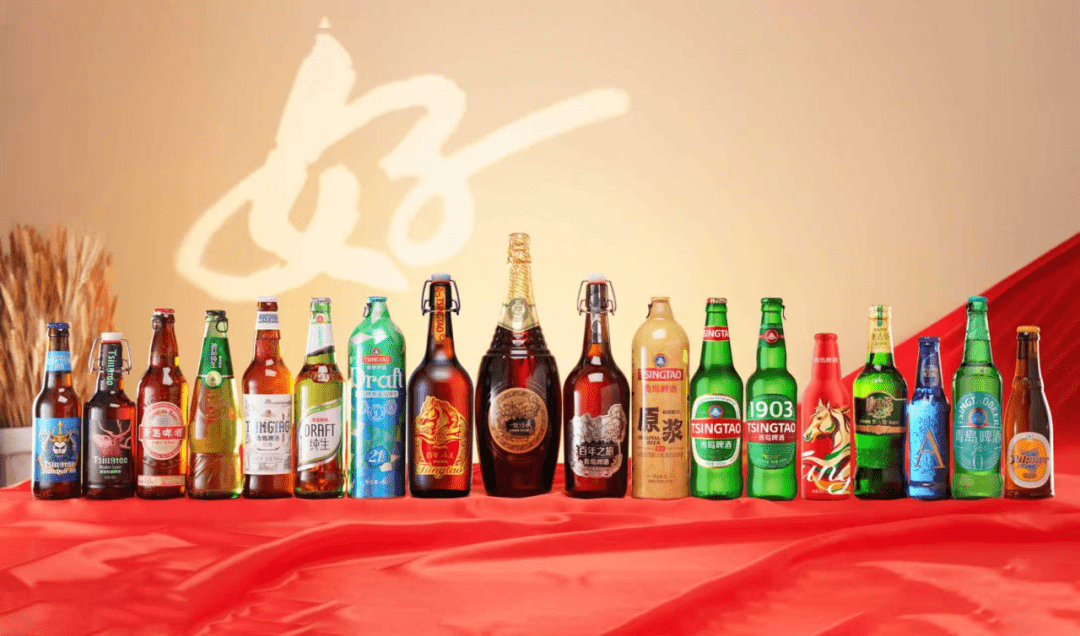
青岛啤酒在半年报中明确,公司持续推进“1+1+1+2+N”产品战略,坚持培育中高端及超高端战略大单品。今年6月,公司正式发布焕新升级的经典1903及超干系列产品,其中100%全麦酿造的1903成为核心看点,瞄准8—10元价格带。
酒业时报注意到,当行业从“提价”迈入“提心”的精细化新阶段,谁能把产品做出差异化、把品牌做出情感连接,谁才能真正留住消费者。青岛啤酒押注的“全麦、生鲜、0糖轻卡、精酿、无醇低醇”等新赛道,正是对这一趋势的回应。
渠道变局中的新打法
营收承压的另一面,是渠道结构的深刻变革。
上半年,青岛啤酒加速布局即时零售、高端餐饮等高潜力渠道,线上、即时零售及现代零售销量均创历史新高,即时零售连续6年保持高速增长。
这不是一句空话。今年7月,京东与青岛啤酒发起“点亮烟火计划”,依托京东的供应链和数字化运营能力,通过包销、联名、新品定制等方式打造系列爆款产品。公司管理层在投资者交流中明确表示,即时零售是确定性增长渠道,未来将推进即时零售业务的优化。
传统渠道与新兴渠道的协同,正在重构啤酒的销售版图。浙商证券研报指出,啤酒行业进入量稳价升阶段,高端化和非即饮渠道扩容是主要趋势和竞争关键。太平洋证券也提出,啤酒业正经历“场景重塑、渠道重构、产品重铸”的三维驱动。
青岛啤酒的渠道变革,本质上是在重新定义“啤酒在哪里被消费”——从餐饮店的餐桌,到家庭冰箱、户外露营、音乐节现场。这种“去场景化”的渠道拓展,恰恰是对冲传统餐饮渠道疲软的关键一招。
39.2亿净利润,放在青岛啤酒的历史坐标中并不算惊艳。但如果放在2026年啤酒行业整体承压、消费需求偏弱的大背景下,这份成绩单的“稳”字背后,是一家百年企业应对周期变化的战略定力。
营收可以承压,但结构必须升级;销量可以波动,但现金流必须健康——这或许就是青岛啤酒给出的答案。
在酒业时报看来,啤酒行业的下半场,比的不是谁跑得快,而是谁走得稳。当潮水退去,真正有护城河的企业,才能在存量博弈中持续拿到属于自己的份额。
While the industry as a whole treaded water and competitors posted double-digit profit growth, Tsingtao Beer carved out its own growth trajectory with a “slightly positive” interim report.
On August 26, Tsingtao Beer released its first-half 2026 results.
Product sales of 4.5 million kilolitres, operating revenue of RMB 19.65 billion, and net profit attributable to shareholders of RMB 3.92 billion. Behind these three core figures lies a steady-and-progressive report card from this century-old brewery in an era of stock-market competition.
But in the view of JiuYe Times, the real significance of this earnings report is not the RMB 3.92 billion figure itself, but what it reveals about a fundamental shift in the competitive logic of the beer industry – when the industry’s volume ceiling is within reach, competition has shifted from “who sells more” to “who sells the right products.”
The “Quality” Behind Modest Profit Growth
First, the numbers. First-half revenue of RMB 19.65 billion, down 4.08% year-on-year; net profit attributable to shareholders of RMB 3.92 billion, up a marginal 0.4% year-on-year. Looking at Q2 alone: revenue of RMB 9.37 billion, down 6.7% year-on-year; net profit attributable to shareholders of RMB 2.12 billion, down 3.4% year-on-year.
Revenue declining while profit slightly increasing – this is a seemingly contradictory set of figures.
Some analysts attribute the profit stability primarily to increased investment income, reduced marketing expenses, and lower raw material costs. This is indeed true. In the first half, the company’s advertising and promotional expenses fell sharply by 33%, saving over RMB 200 million in costs.
But the other side of the coin is equally noteworthy: net cash flow from operating activities reached RMB 5.505 billion, up 14.69% year-on-year. Despite the revenue decline, cash flow surged – indicating improved collection efficiency, channel control, and cash generation capability.
Xiangcai Securities noted in a May 2026 research report that the company is transitioning from “profit recovery driven by cost tailwinds” to a new phase of “continued structural upgrading + peak-season volume recovery.”
Whether profit growth is “respectable” depends on whether it comes at the expense of the future or is accumulated for the future. With RMB 5.5 billion in operating cash flow, Tsingtao falls into the latter category.
Premiumisation’s Counter-Trend Breakthrough
Against the backdrop of overall volume contraction, Tsingtao Beer’s premiumisation strategy is delivering results.
In the first half, the flagship Tsingtao brand achieved sales of 2.708 million kilolitres, of which mid-to-high-end products accounted for 2.044 million kilolitres, up 2.6% year-on-year. This means mid-to-high-end products now account for over 75% of the flagship brand’s volume.
A cross-industry comparison is telling. In the first half of 2026, national beer production edged up only 0.2% year-on-year, essentially flat. China Resources Beer’s beer business revenue reached RMB 23.67 billion, up 2.2% year-on-year, with above-premium volume growth exceeding 10%; Yanjing Beer’s revenue reached RMB 9.031 billion, up 5.53% year-on-year, with net profit of RMB 1.399 billion, up 26.86% year-on-year; while Chongqing Beer’s revenue was RMB 8.576 billion, down 2.98%, with net profit of RMB 796 million, down 7.98%.
A clear divergence is emerging among industry leaders – the deeper the premiumisation push, the stronger the resilience against market cycles.
Tsingtao Beer made clear in its interim report that it continues to advance its “1+1+1+2+N” product strategy, persistently cultivating mid-to-high-end and super-premium strategic mega-SKUs. In June this year, the company officially launched the refreshed Classic 1903 and Super Dry series, with the 100% whole-malt-brewed 1903 as the core highlight, targeting the RMB 8–10 price band.
JiuYe Times notes that as the industry moves from “price increases” to the new refined stage of “mind-share capture,” those who can differentiate their products and build emotional connections with their brands will truly retain consumers. Tsingtao’s focus on new segments such as “whole malt, fresh beer, zero-sugar light, craft, and non/low-alcohol” is precisely a response to this trend.
New Approaches Amid Channel Transformation
The pressure on revenue is mirrored by profound changes in the channel structure.
In the first half, Tsingtao Beer accelerated its presence in high-potential channels such as instant retail and premium dining. Sales across online, instant retail, and modern retail channels all hit record highs, with instant retail maintaining high-speed growth for six consecutive years.
This is not empty rhetoric. In July this year, JD.com and Tsingtao Beer jointly launched the “Light Up the Flame of Life” initiative, leveraging JD’s supply chain and digital operations capabilities to create a series of hit products through buyout models, co-branding, and new product customisation. Company management made it clear in investor communications that instant retail is a growth channel with certainty, and that optimisation of instant retail operations will be pursued going forward.
The synergy between traditional and emerging channels is reshaping the beer sales landscape. Zheshang Securities research noted that the beer industry has entered a phase of stable volume and rising prices, with premiumisation and off-trade channel expansion being the main trends and competitive battlegrounds. Pacific Securities also highlighted that the beer industry is undergoing a three-dimensional transformation of “scene reshaping, channel restructuring, and product reinvention.”
Tsingtao Beer’s channel transformation is essentially redefining “where beer is consumed” – from restaurant tables to home refrigerators, outdoor camping sites, and music festival grounds. This “de-scenarised” channel expansion is precisely the key countermeasure against weakness in traditional dining channels.
A net profit of RMB 3.92 billion is not particularly impressive in Tsingtao Beer’s historical context. But placed against the backdrop of overall industry pressure and weak consumer demand in 2026, the “stability” behind this performance reflects a century-old company’s strategic resolve in navigating cyclical change.
Revenue may come under pressure, but the structure must upgrade; volume may fluctuate, but cash flow must remain healthy – this is perhaps the answer Tsingtao Beer has offered.
In the view of JiuYe Times, the second half of the beer industry is not about who runs faster, but who walks more steadily. When the tide recedes, companies with true moats will continue to secure their share in the stock-market game.
原创文章版权归本网所有;转载文章归原作者所有。发布者:酒业时报,转载请注明出处:https://www.thewinetimes.com/gongsi/12168