酒业深度调整周期之下,经销商、品牌方热议的核心话题已经变了:不再是囤货、涨价,而是如何摆脱过去依靠关系压货的旧套路,找到面向C端的真实动销路径。
焦虑的背后是酒业产量连续十年下滑,近半数上市酒企营收负增长,经销商从“囤货等涨”转向“小单快补”。而在苏皖大地上,今世缘交出的二季度报表逆势翻红——营收同比增长14.11%,净利润同比增长19.17%。
在行业深度收缩的当下,这组数据的意义远超数字本身。它或许在告诉行业:当旧路径失灵时,新路径已经在生长。
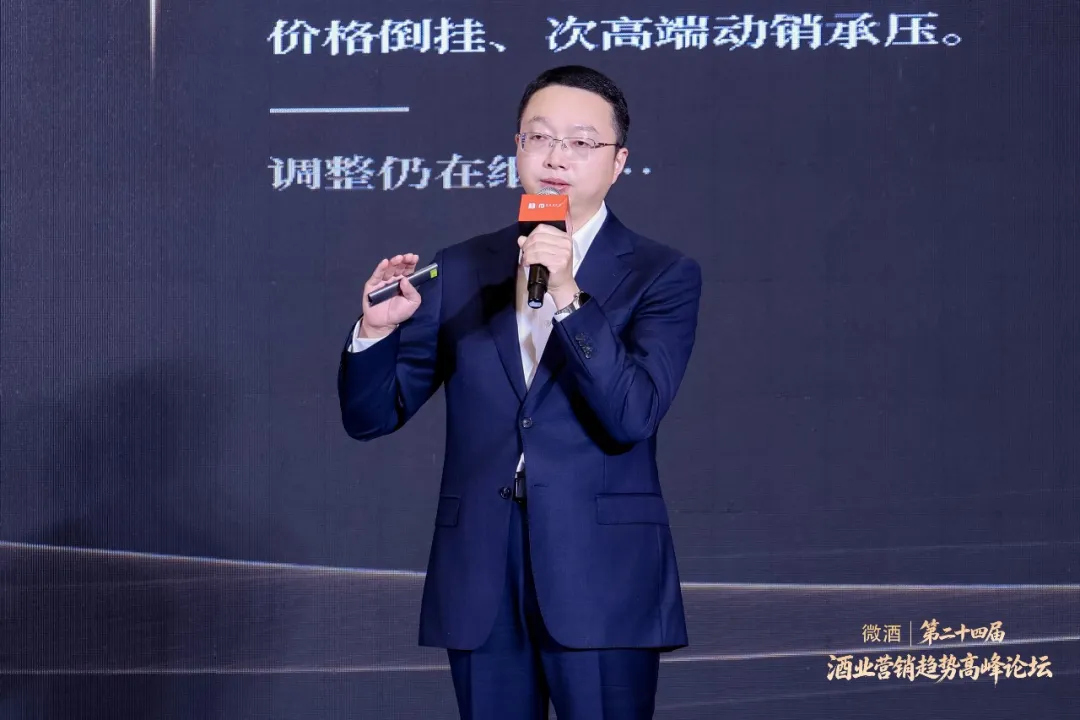
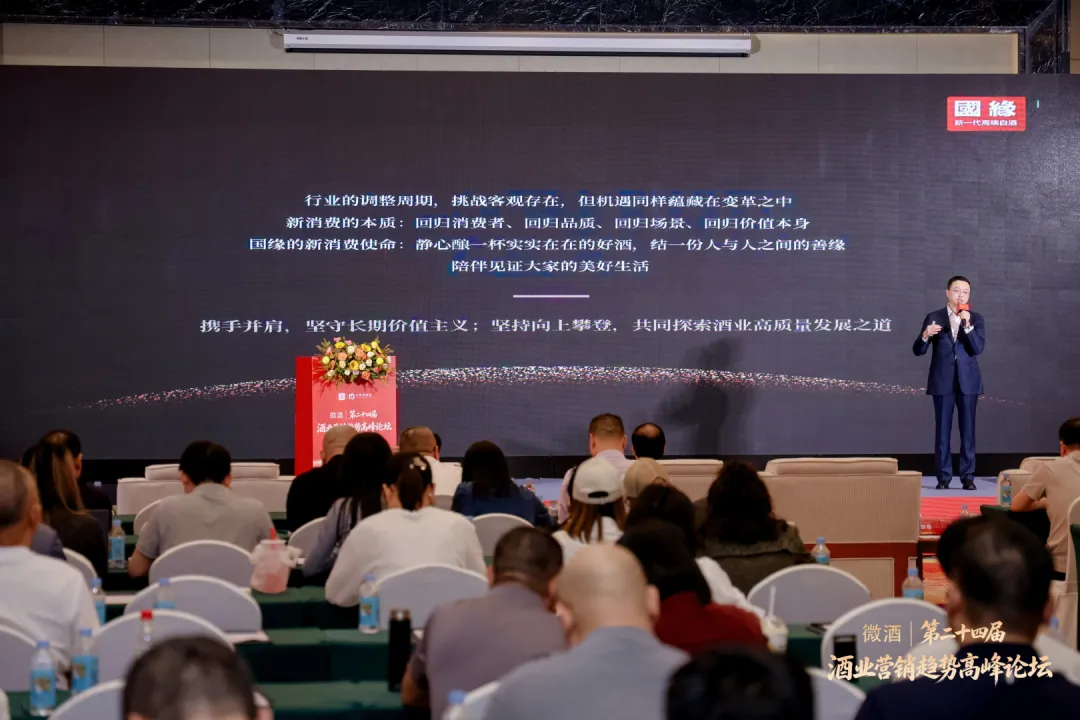
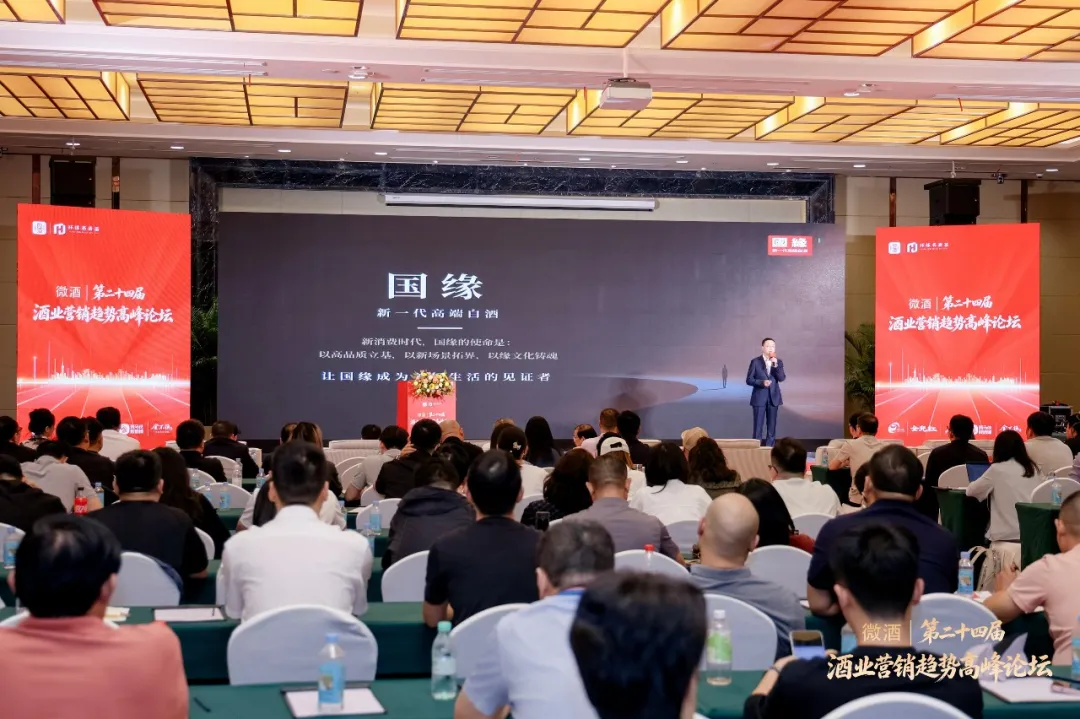
日前,在微酒・第二十四届酒业营销趋势高峰论坛上,江苏今世缘酒业党委委员、副总经理胡跃吾发表了题为《服务时代见证美好·国缘的新消费使命和战略背景》的主题分享,全面解码了国缘品牌“取势、明道、立愿”的战略思考和三大洞察。
结合胡跃吾的分享,在酒业时报看来,今世缘的Q2“转正”,本质上是一个坚持了22年的“慢品类”策略终于等来了消费趋势的拐点。这条从42度中度白酒起步的差异化道路,正在从“小众选择”变为“主流共识”。
白酒的产能过剩是周期性的,但消费结构的迁移是趋势性的。今世缘的样本价值不在于一个季度的数据反弹,而在于它证明了:在一个缩量市场中,坚持做“对的事”比追逐“快的钱”更有生命力。
触底回升的“信号弹”:一组逆势数据的深层解读
2026年8月,今世缘交出半年报。上半年营收64.35亿元、净利润20.82亿元,同比仍在下滑。但拆开来看,Q1同比下滑15.23%,Q2却强势反弹——营收21.13亿元,同比增长14.11%,净利润6.97亿元,同比增长19.17%。
东方证券研报指出,公司“经营基调为稳百亿大盘、稳终端信心”,经营策略稳健务实,在当前外部环境下顺势而为。方正证券则更为直接地判断,今世缘“Q2经营表现全面向好,拐点信号快于预期”。
一个更值得关注的细节是产品结构。2025年全年,今世缘代表100至300元价位带的特A类产品营收32.69亿元,毛利率达65.97%,同比增加0.60个百分点;而300元以上的特A+类产品营收同比下降16.89%。到了2026年Q1,特A类产品同比仅下降1.6%,在整体下滑中表现出极强的韧性。
这组数据的含义很清楚:当前行业最具确定性的增长,不在千元价格带,而在百元大众价格带。
华创证券的国庆渠道调研印证了这一判断:高端礼赠和100元大众价格带相对稳健,次高端商务宴席承压明显,动销呈现“两头稳、中间弱”的格局。国海证券食品饮料首席分析师刘旭德进一步指出,需求正从以商务、礼赠为主的“悦人”场景,向自饮、聚饮等“悦己”场景拓展,C端消费扩容是行业的长期方向。
换言之,今世缘的Q2转正并非偶然。当行业还在为高价位带的库存出清焦灼时,它的产品矩阵恰好卡位在了消费需求迁移的方向上。
他山之石:日本清酒的“降度史”与国缘的“先见之明”
理解国缘坚持中度路线的价值,不妨将视线暂时移出中国白酒行业。
广发证券在一份中日食品饮料复盘中指出,日本清酒行业自1973年至今呈现“量减价升、中小企业出清”的走势,与中国白酒2016年以后的表现高度相似。而日本清酒在这一过程中的关键趋势之一,就是低度化、饮料化催生了多款大单品。
上世纪60年代,日本税制政策调整叠加消费偏好转变,推动清酒行业走向低度化,不少产品酒精度降至20度以下,催生全新消费场景与品类空间。
这一历史轨迹,与国缘的22年坚守形成了耐人寻味的呼应。
2004年国缘品牌创立时,正值白酒行业“高度为王”的黄金时代。52度、53度是市场绝对主流,42度白酒被视为“不够劲”。但今世缘酒业选择了一条“所有人都不走的路”——旗舰单品国缘四开定价突破400元,度数却只做42度。
这在当时看来是冒险,拉长时间轴看却是超前。经过五代产品迭代,今世缘酒业攻克了“降度不降口感”的行业技术难题,确立了“低而不淡,幽雅醇厚”的差异化品质标签。国缘四开、对开、V9三款产品均获评绿色食品A级认证。
酒业时报认为,国缘的中度路线选择,本质上是一种“品类时间窗口”的战略押注。当行业普遍追求高度酒的高溢价时,国缘用22年建立了一个竞争者难以快速复制的技术壁垒和消费者认知。如今,当“少喝点、喝好一点、喝轻松一点”成为消费共识时,这个时间窗口终于打开了。
从“渠道蓄水池”到“用户活水”:一场经营范式的底层切换
如果说产品策略是“做什么”,那渠道策略就是“怎么卖”。而在2026年,白酒行业的渠道逻辑正在经历一场根本性的重构,这也是本次南京糖酒会行业讨论的核心议题。
知趣咨询总经理蔡学飞对2026年双节白酒市场的观察颇为精准:“节前不抢货、节后不跳水,渠道从赌行情压货转向‘小单快补、看开瓶说话’。”他进一步指出,酒行业底层逻辑正从“酒厂压任务→经销商囤货→节前冲量”的回款驱动,切换为“控配额、治窜货、做宴席、返消费者”的动销驱动。
这个转变的管理学意义,可以用一个跨界概念来类比——DTC(Direct to Consumer,直达消费者)模式。在快消品领域,DTC模式的核心价值在于品牌直接掌握消费者数据,实现精准运营,反向驱动产品研发与营销策略。白酒行业虽然很难完全复制互联网品牌的DTC路径,但“费用直达C端、考核绑定开瓶”的做法,本质上是同一个逻辑的线下版本。
今世缘在这个方向上的布局值得关注。2026年9月,公司接受109家机构调研时明确提出,坚持“出货与动销匹配”,不会为追求短期报表给渠道压货。半年报数据也佐证了这一点:Q2经营现金流净额同比增长50.33%,终端动销与出货的匹配度持续改善。
在酒业时报看来,白酒行业正在经历的渠道变革,其实质是从“库存转移”到“消费触达”的范式转换。过去二十年,白酒的增长引擎是渠道蓄水池的不断扩容;未来十年,真正的竞争力将取决于品牌对终端消费者的触达深度和运营精度。今世缘率先将“C端用户运营”提升至战略高度,这步棋的深远意义可能要在两三年后才会被行业充分认识。
“三十而立”的今世缘:国缘品牌的长期主义方法论
2026年,今世缘品牌迎来创立三十周年。1996年,今世缘在南京金陵饭店打出第一块品牌广告招牌;而旗下国缘品牌自2004年诞生,用二十余年,推动这家从苏北涟水走出来的区域酒企,从“淮安飘香名片”成长为中国白酒上市公司十强。
站在三十周年的节点上回望,国缘品牌的三次战略迭代构成了清晰的价值跃迁路径:2004年以“成大事,必有缘”切入高端商务场景;2023年升级为“中国新一代高端白酒”;2026年进一步提出“国缘・新一代高端白酒”定位。
三次迭代的背后,是对消费趋势变化的持续回应。但有一条主线始终未变:中度高端。
酒业时报认为,这恰恰是今世缘战略中最值得同行研究的部分。在一个充满短期诱惑的行业里,22年坚持一条技术路线和品类定位,需要的不仅是战略定力,更是对消费趋势底层逻辑的深刻判断。用胡跃吾在糖酒会上的表述来说——“坚持是最慢的武器,也是最长的护城河。”
在行业深度调整期,今世缘并未收缩对未来的投入。按照规划,到2027年企业陶坛储能规模将提升至43万吨,为高端产品矩阵的长期发展储备产能。这种在周期底部夯实产能基础的动作,传递出的信号很明确:对行业中长期走势的看好,从来不是嘴上说说,而是用真金白银的投入来投票。
白酒行业的调整仍在继续。2026年上半年,全国规模以上企业白酒产量同比下降4.7%,行业整体营收和利润总额分别同比下降7.0%和17.7%。
但调整的另一面是分化。19家A股白酒企业上半年营收排名前五的占比从去年同期的80.02%提升至82.66%,利润占比从88.44%提升至91.18%。资源正在向有品牌力、有产品结构韧性、有渠道治理能力的企业集中。
今世缘在这个过程中的表现,或许为区域酒企提供了一个穿越周期的参考样本:不做最激进的事,但做最对的事;不追求最快的增长,但守住最稳的节奏。当消费结构的潮水转向“舒适、健康、理性”时,那条22年前就修好的河道,恰好承接了新的水流方向。
Amid the deep adjustment cycle of the liquor industry, the core topics debated by distributors and brands have changed: no longer stockpiling and price increases, but how to break free from the old playbook of relying on relationships to push inventory, and find genuine C-end sell-through pathways. Behind the anxiety is a decade-long decline in liquor output, negative revenue growth at nearly half of listed liquor companies, and distributors shifting from “stockpiling while waiting for price rises” to “small orders and quick replenishment.” Yet on the lands of Jiangsu and Anhui, Jinshiyuan delivered a counter-trend turnaround in its second-quarter report — revenue up 14.11% year-on-year and net profit up 19.17% year-on-year. Amid the industry’s deep contraction, the significance of these figures far exceeds the numbers themselves. It may be telling the industry: when the old path fails, a new path is already growing.
Recently, at the Weijiu · 24th Liquor Industry Marketing Trends Summit Forum, Hu Yuewu, Party Committee Member and Deputy General Manager of Jiangsu Jinshiyuan Liquor, delivered a keynote speech titled “Witnessing Beauty in the Era of Service · Guoyuan’s New Consumption Mission and Strategic Background,” comprehensively decoding the strategic thinking of “seizing momentum, clarifying the way, and establishing the vow” behind the Guoyuan brand, along with three major insights.
Drawing on Hu Yuewu’s sharing, in the view of JiuYe Times, Jinshiyuan’s Q2 “return to positive” is essentially a 22-year adherence to a “slow category” strategy finally meeting the inflection point of consumer trends. This differentiated path, which began with 42-degree medium-alcohol baijiu, is transforming from a “niche choice” into a “mainstream consensus.” Overcapacity in baijiu is cyclical, but the migration of consumption structure is trend-driven. The sample value of Jinshiyuan lies not in a single quarter’s data rebound, but in proving that in a shrinking market, adhering to “doing the right thing” has more vitality than chasing “fast money.”
PART 01
The “Signal Flare” of Bottoming Out and Recovery: A Deep Reading of a Set of Counter-Trend Data
In August 2026, Jinshiyuan released its semi-annual report. First-half revenue was RMB 6.435 billion and net profit was RMB 2.082 billion, still declining year-on-year. But broken down, Q1 declined 15.23% year-on-year, while Q2 rebounded strongly — revenue of RMB 2.113 billion, up 14.11% year-on-year, and net profit of RMB 697 million, up 19.17% year-on-year.
An Orient Securities research report pointed out that the company’s “operating tone is to stabilise the ten-billion-yuan base and stabilise terminal confidence,” with steady and pragmatic operating strategies, acting in line with the current external environment. Founder Securities was more direct in its judgement that Jinshiyuan’s “Q2 operating performance improved comprehensively, with inflection signals faster than expected.”
A more noteworthy detail is the product structure. In the full year of 2025, Jinshiyuan’s Special A category products, representing the RMB 100–300 price band, generated revenue of RMB 3.269 billion, with a gross margin of 65.97%, up 0.60 percentage points year-on-year; while Special A+ products above RMB 300 saw revenue decline 16.89% year-on-year. By Q1 2026, Special A category products declined only 1.6% year-on-year, demonstrating extremely strong resilience amid the overall decline.
The meaning of this data is clear: the most certain growth in the current industry is not in the thousand-yuan price band, but in the hundred-yuan mass price band. Huachuang Securities’ National Day channel research confirmed this judgement: high-end gifting and the RMB 100 mass price band were relatively stable, while sub-premium business banquets came under notable pressure, with sell-through showing a pattern of “stable at both ends, weak in the middle.”
Liu Xude, Chief Food and Beverage Analyst at Guohai Securities, further pointed out that demand is expanding from “pleasing others” scenarios centred on business and gifting toward “pleasing oneself” scenarios such as self-drinking and social drinking, and that C-end consumption expansion is the industry’s long-term direction. In other words, Jinshiyuan’s Q2 return to positive is no accident. While the industry is still anxious about clearing inventory in high price bands, its product matrix happens to be positioned precisely in the direction of consumer demand migration.
PART 02
Learning from Others: The “Alcohol Reduction History” of Japanese Sake and Guoyuan’s “Foresight”
To understand the value of Guoyuan’s adherence to the medium-alcohol route, it is worth temporarily shifting our gaze outside China’s baijiu industry. In a review of Chinese and Japanese food and beverage sectors, GF Securities pointed out that the Japanese sake industry has shown a trend of “declining volume, rising prices, and the clearing out of small and medium-sized enterprises” since 1973, highly similar to the performance of Chinese baijiu after 2016. One of the key trends in Japanese sake during this process was that lower alcohol content and beverage-isation gave rise to multiple flagship products.
In the 1960s, adjustments to Japan’s tax policies combined with shifts in consumer preferences pushed the sake industry toward lower alcohol content, with many products dropping below 20 degrees, giving rise to entirely new consumption scenarios and category space. This historical trajectory forms an intriguing echo with Guoyuan’s 22-year adherence.
When the Guoyuan brand was founded in 2004, it was the golden age of “high alcohol is king” in the baijiu industry. 52 degrees and 53 degrees were the absolute mainstream, and 42-degree baijiu was seen as “not strong enough.” But Jinshiyuan chose a path “that no one else would take” — the flagship product Guoyuan Sikail was priced above RMB 400, yet made at only 42 degrees. This seemed risky at the time, but looking at the longer timeline, it was ahead of its time.
After five generations of product iteration, Jinshiyuan solved the industry’s technical challenge of “reducing alcohol without reducing taste,” establishing a differentiated quality label of “low but not bland, elegant and mellow.” The three products Guoyuan Sikail, Duikail, and V9 have all received Green Food Grade A certification.
In the view of JiuYe Times, Guoyuan’s choice of the medium-alcohol route is essentially a strategic bet on a “category time window.” While the industry generally pursued the high premiums of high-alcohol liquor, Guoyuan spent 22 years building a technical barrier and consumer perception that competitors find difficult to quickly replicate. Now, when “drink less, drink better, drink more comfortably” has become a consumer consensus, this time window has finally opened.
PART 03
From “Channel Reservoir” to “User Living Water”: A Fundamental Switch in Business Paradigm
If product strategy is “what to do,” then channel strategy is “how to sell.” In 2026, the channel logic of the baijiu industry is undergoing a fundamental restructuring, which was also the core topic of industry discussion at the Nanjing Tangjiu Fair.
Cai Xuefei, General Manager of Zhiqu Consulting, offered a rather precise observation of the 2026 double-festival baijiu market: “No scrambling for goods before the festival, no plunging after the festival; channels have shifted from gambling on market conditions and stockpiling to ‘small orders and quick replenishment, letting bottle openings speak.'” He further pointed out that the underlying logic of the liquor industry is shifting from the collection-driven model of “distillery pushes targets → distributors stockpile → pre-festival volume push” to a sell-through-driven model of “controlling quotas, governing cross-region diversion, doing banquets, and rewarding consumers.”
The management significance of this shift can be compared to a cross-industry concept — the DTC (Direct to Consumer) model. In the FMCG sector, the core value of the DTC model lies in brands directly mastering consumer data, achieving precise operations, and reverse-driving product development and marketing strategies. Although the baijiu industry finds it difficult to fully replicate the DTC path of internet brands, the practice of “expenses reaching the C-end directly and assessments tied to bottle openings” is essentially the offline version of the same logic.
Jinshiyuan’s layout in this direction is worth attention. In September 2026, when the company received research from 109 institutions, it explicitly stated its adherence to “matching shipments with sell-through” and that it would not push inventory onto channels for the sake of short-term financial statements. The semi-annual report data corroborates this: Q2 net operating cash flow grew 50.33% year-on-year, with the match between terminal sell-through and shipments continuing to improve.
In the view of JiuYe Times, the channel transformation the baijiu industry is undergoing is essentially a paradigm shift from “inventory transfer” to “consumer reach.” Over the past two decades, the growth engine of baijiu was the continuous expansion of the channel reservoir; over the next decade, true competitiveness will depend on the depth of brand reach and precision of operations with terminal consumers. Jinshiyuan has taken the lead in elevating “C-end user operations” to a strategic height, and the far-reaching significance of this move may only be fully recognised by the industry two or three years from now.
PART 04
Jinshiyuan at “Thirty Years of Standing”: The Long-Termist Methodology of the Guoyuan Brand
In 2026, the Jinshiyuan brand celebrates its 30th anniversary. In 1996, Jinshiyuan put up its first brand advertising sign at the Jinling Hotel in Nanjing; and its Guoyuan brand, born in 2004, has spent more than two decades propelling this regional liquor enterprise from Lianshui in northern Jiangsu from a “fragrant calling card of Huai’an” to one of China’s top ten listed baijiu companies.
Standing at the 30th anniversary milestone and looking back, the three strategic iterations of the Guoyuan brand constitute a clear path of value elevation: in 2004, it entered the high-end business scenario with “Great achievements are fated”; in 2023, it upgraded to “China’s new-generation high-end baijiu”; and in 2026, it further proposed the positioning of “Guoyuan · New Generation High-End Baijiu.” Behind these three iterations is a continuous response to changes in consumer trends. But one mainline has never changed: medium-alcohol premium.
In the view of JiuYe Times, this is precisely the part of Jinshiyuan’s strategy most worth studying by peers. In an industry full of short-term temptations, adhering to one technical route and category positioning for 22 years requires not only strategic resolve, but also a profound judgement of the underlying logic of consumer trends. As Hu Yuewu put it at the Tangjiu Fair — “Persistence is the slowest weapon, and also the longest moat.”
During the industry’s deep adjustment period, Jinshiyuan has not contracted its investment in the future. According to the plan, by 2027 the company’s clay jar storage capacity will increase to 430,000 tonnes, reserving production capacity for the long-term development of its high-end product matrix. This move to consolidate production capacity foundations at the bottom of the cycle sends a clear signal: optimism about the industry’s medium- and long-term trajectory is never just talk — it is voting with real money.
The adjustment in the baijiu industry continues. In the first half of 2026, national above-scale enterprise baijiu output declined 4.7% year-on-year, and the industry’s overall revenue and total profit declined 7.0% and 17.7% respectively. But the other side of adjustment is divergence. Among 19 A-share baijiu companies, the top five by first-half revenue increased their share from 80.02% in the same period last year to 82.66%, and their profit share rose from 88.44% to 91.18%. Resources are concentrating toward enterprises with brand strength, product structure resilience, and channel governance capability.
Jinshiyuan’s performance in this process may provide regional liquor companies with a reference sample for transcending cycles: do not do the most radical thing, but do the most right thing; do not pursue the fastest growth, but hold the steadiest rhythm. When the tide of consumption structure turns toward “comfort, health, and rationality,” that river channel built 22 years ago happens to catch the new direction of the current.
原创文章版权归本网所有;转载文章归原作者所有。发布者:酒业时报,转载请注明出处:https://www.thewinetimes.com/gongsi/13071